Austin's affordability gap is not a rent-growth guarantee
Contributed perspective | Austin multifamily investment
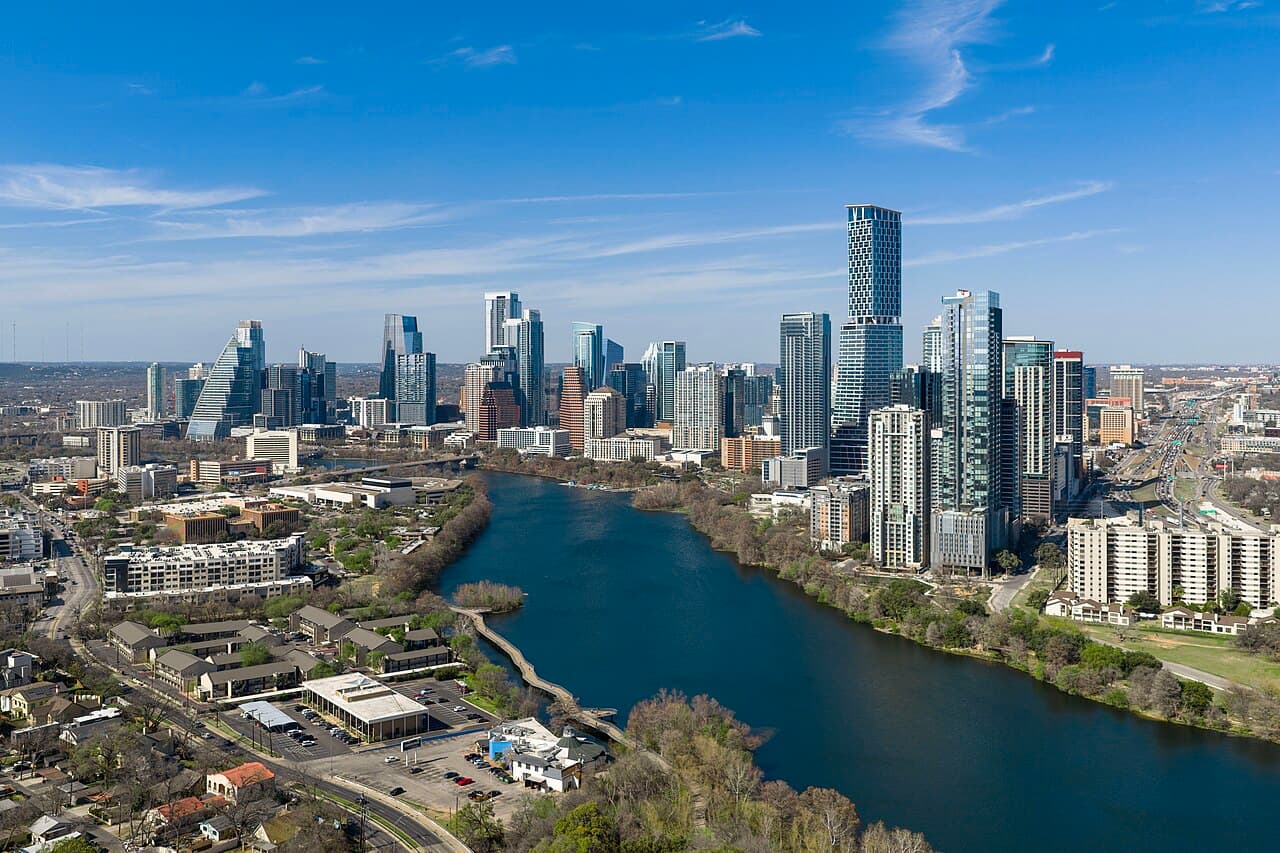
High homeownership costs can make renting comparatively attractive, but they do not automatically strengthen the economics of owning multifamily property. Austin offers a useful example of that distinction.
By the third quarter of 2026, borrowing costs remained elevated and the monthly cost difference between renting and buying was substantial. At the same time, Zillow's renter-engagement indicator for the Austin metro was rising sharply. Those indicators are consistent with affordability pressure contributing to rental demand, but they do not establish that the affordability gap caused the increase in renter demand. Zillow September 2026 Rent Report.
Apartment-market data also showed that stronger renter interest had not yet translated into strong pricing power: effective rents remained below year-earlier levels while the market continued to absorb a large recent supply wave. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
For multifamily investors, that combination raises a practical question: how much can affordability pressure support rent growth when substantial apartment supply is competing for the same renters?
The Rent-Versus-Own Gap Is Wide
For household-income context, the U.S. Census Bureau's 2024 American Community Survey reported median household income of $99,897 for the Austin-Round Rock-San Marcos metropolitan area. This is the latest annual ACS income observation used here; I do not extrapolate it to Q3 2026. U.S. Census Bureau, Household Income in States and Metropolitan Areas: 2024, Appendix Table 2.
Freddie Mac's Primary Mortgage Market Survey recorded a 30-year fixed mortgage rate of 7.03% on September 24, 2026. That weekly observation describes financing conditions; it is not a reconstruction of Zillow's separate monthly ownership-cost estimate. Freddie Mac PMMS Archive.
Zillow's September 2026 market report placed the typical Austin metro home value (ZHVI) at $416,134. Zillow's September rent report listed the Austin metro's Zillow Observed Rent Index (ZORI) at $1,603 per month and its typical monthly payment for a new homeowner at $3,696, based on 10% down and a 30-year fixed mortgage. Zillow September 2026 Market Report. Zillow September 2026 Rent Report.
Comparing Zillow's Published Monthly Estimates
Zillow's rent report compares a $3,696 modeled monthly payment for a new Austin homeowner, assuming 10% down and a 30-year fixed mortgage, with a typical asking rent of $1,603. Using those published figures gives the following difference. It does not independently reconstruct the ownership-cost model. Zillow September 2026 Rent Report.
$3,696 ownership payment - $1,603 rent = $2,093 per month
$2,093 x 12 = $25,116 per year
The $3,696 figure is Zillow's total monthly payment measure, not principal and interest alone. Its methodology includes mortgage payments, mortgage insurance where applicable, regionally estimated homeowners insurance and property taxes, and maintenance assumed at 0.5% of home value annually. HOA fees are excluded. These are modeled costs, not an individual homeowner's bills. Zillow Affordability Methodology.
This comparison is an affordability illustration, not a claim that a particular household would save exactly $25,116 by renting. The rental and ownership properties are not necessarily identical, and actual costs vary with property type, location, credit profile, insurance, taxes, transaction costs and household circumstances.
What the Zillow Rental Indicators Actually Measure
The $1,603 rent figure is Zillow's metro-level ZORI. Zillow describes ZORI as a repeat-rent index that measures changes in asking rents over time, controls for changes in the quality of available rental stock, and uses Census-based weights so the index better represents the broader rental market rather than only the listings currently available on Zillow. Zillow publishes ZORI at metropolitan and other geographic levels. Zillow ZORI Methodology. Zillow Housing Data.
The 49.3% year-over-year renter-demand figure is Zillow's Observed Renter Demand Index (ZORDI) for the Austin metro. Zillow describes ZORDI as a smoothed measure of engagement with rental listings on Zillow that is used as a proxy for changes in rental demand. It is not a count of signed leases. Zillow publishes ZORDI at the MSA level and for multiple rental-property categories. Zillow September 2026 Rent Report. Zillow Housing Data.
In September 2026, Austin's ZORDI was up 49.3% year over year, while ZORI was up only 0.7% year over year. The coexistence of stronger listing engagement and modest rent growth is consistent with a market where renter interest is healthy but landlords' pricing power remains constrained; it does not, by itself, establish why renter engagement increased. Zillow September 2026 Rent Report.
Apartment-Market Data Show the Role of Supply
Commercial multifamily operating data tell a similar story from a different property universe. Cushman & Wakefield's Q3 2026 Austin Multifamily MarketBeat reported average effective rent of $1,415 per unit, down 1.9% year over year. That figure should not be treated as directly interchangeable with Zillow's $1,603 ZORI because the two providers use different property universes and methodologies. I use them as separate directional indicators rather than combining their levels. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
Cushman & Wakefield reported 5,245 multifamily units delivered during Q3 2026, bringing year-to-date completed deliveries to 10,370 units. At quarter-end, another 13,543 units were under construction, down 32.0% from a year earlier. The figures indicate that Austin was still digesting substantial recent supply even as the active construction pipeline was contracting. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
Absorption Is Improving the Balance
Demand was absorbing new inventory at a meaningful pace. Cushman & Wakefield reported 6,585 units of net absorption in Q3, 1,340 more than the 5,245 units delivered during the quarter. Year-to-date net absorption reached 17,952 units, about 1.7 times year-to-date completions. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
Market vacancy fell to 9.0%, down 80 basis points quarter over quarter and 100 basis points year over year. Seventeen of the firm's 22 Austin submarkets recorded year-over-year vacancy declines. Those are constructive operating signals, but they do not mean rent growth had fully recovered: average effective rent was still 1.9% below its year-earlier level, and only nine of 22 submarkets recorded positive year-over-year effective-rent growth. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
Affordability Supports a Renter Pool, Not Necessarily Returns
The Austin evidence is consistent with a market in which the rent-versus-own gap helps make renting financially attractive while a large apartment supply cycle limits landlords' ability to convert renter interest immediately into rent growth. The data presented here do not prove that high ownership costs caused Austin's increase in renter engagement; they show that the two conditions coexisted while rent growth remained modest.
For an investor, the relevant underwriting question is therefore not simply whether households have a financial reason to rent. It is whether demand is growing fast enough relative to available and incoming supply to create sustainable pricing power at the property level. Vacancy, absorption, competing deliveries, concessions, submarket conditions and the remaining construction pipeline all matter.
The operating side matters as well. Property taxes, insurance, payroll, maintenance, utilities and other expenses affect net operating income even when occupancy improves. Financing costs can also affect acquisition pricing and leveraged returns independently of renter demand. That is why the proposition that 'homeownership is unaffordable, therefore multifamily returns should rise' is incomplete.
Observed Results Versus Outlook
The observed Q3 2026 evidence is encouraging in several respects: absorption exceeded deliveries, vacancy declined, the construction pipeline contracted, and the pace of completed deliveries moderated. At the same time, market-wide effective rent remained below its year-earlier level. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
Any conclusion that lower future supply will restore stronger rent growth is therefore a forecast, not an observed result. Cushman & Wakefield describes the market as rebalancing as supply pressure recedes, but employment, household formation, migration, renter incomes, remaining deliveries, concessions, operating expenses and financing conditions could all affect the outcome. Cushman & Wakefield Austin Multifamily MarketBeat, Q3 2026.
For an investor assessing Austin today, the more defensible conclusion is not that affordability guarantees stronger multifamily returns. It is that renter-engagement indicators remain strong while the market works through the effects of a large supply cycle. Housing affordability helps frame why renting may remain financially attractive; supply and operating fundamentals determine how much of that demand reaches an investor's bottom line.
Author Bio
Jai Perkash is the Founder and Publisher of Prozameen, an independent real estate research and educational platform focused on property markets, housing affordability, investment analysis and market fundamentals. His work focuses on reviewing housing, rental, financing and development data to produce practical market analysis for property investors and readers.
Disclosure
This article is an independent editorial contribution. I have no sponsor, client, referral or investment relationship connected to the Austin multifamily market or to the analysis presented here.
Free CRE News Briefing
Editor-curated commercial real estate stories, delivered to your inbox. Confirm your email to join.